
When does a vacation actually cost money? My wife and I disagree
I started my career as an accountant. I was working toward the CPA, doing the kind of work you would expect, and then I moved into operations, and from there into tech, where I have spent the last stretch in strategy and operations roles. Reconciling things stopped being my job a long time ago.
Nobody told my brain. It is still slightly hardwired to think like an accountant, and most of the time that is a harmless quirk. Occasionally it turns an ordinary Sunday into a debate with my wife about the nature of an expense.
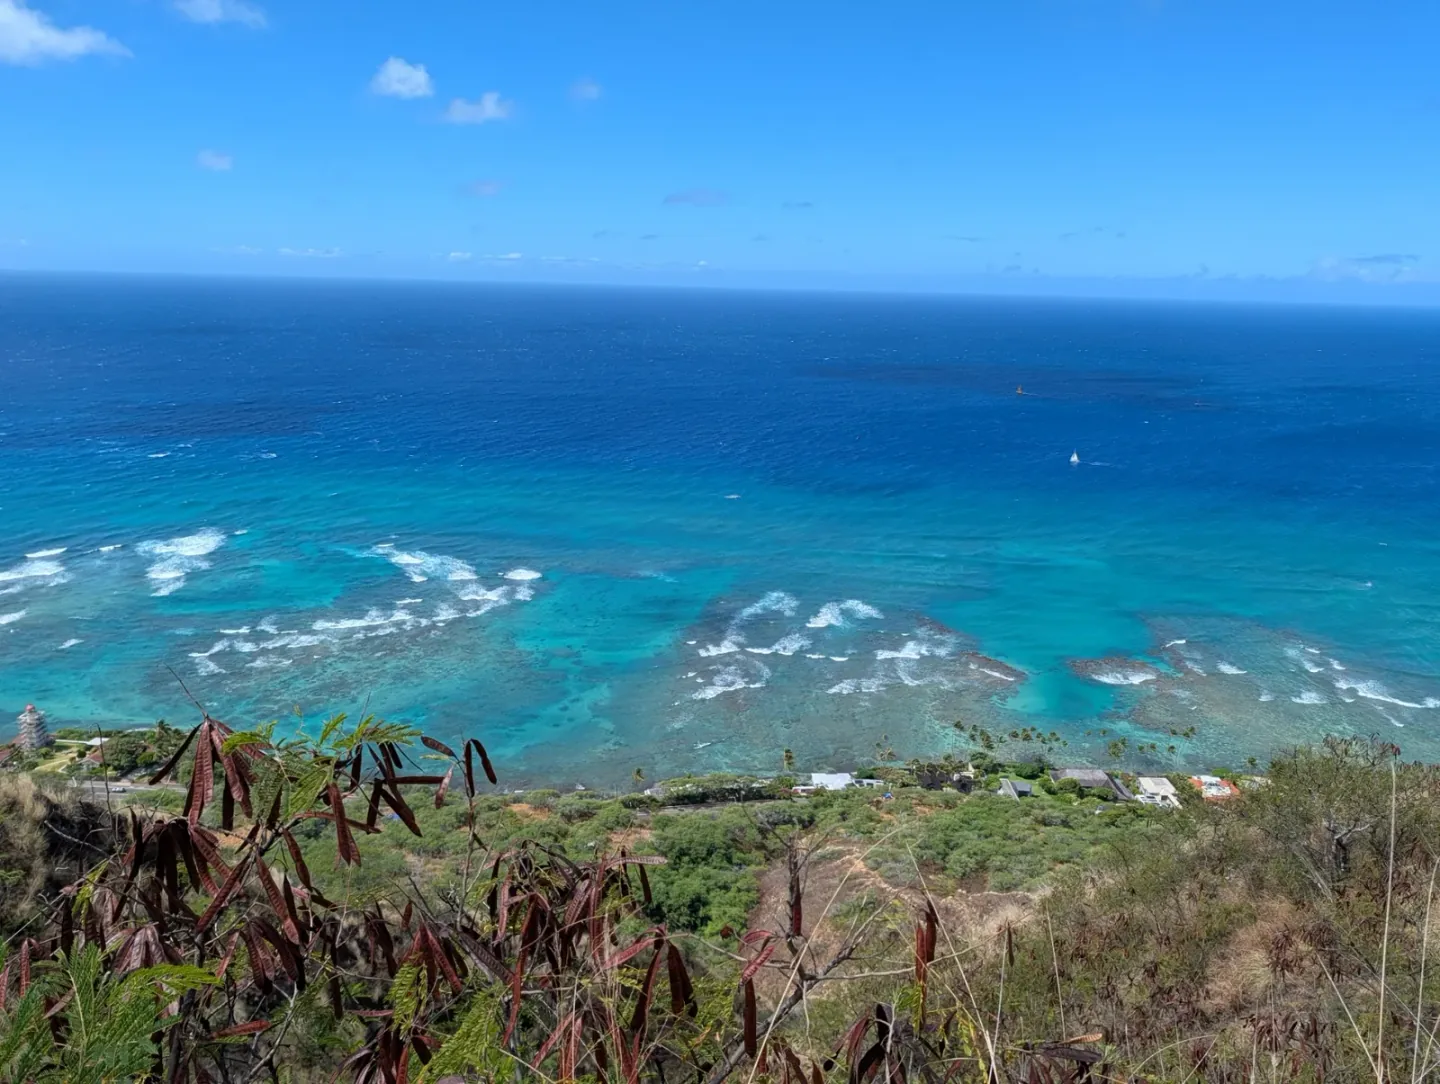
We landed back from Hawaii on a Thursday. By Sunday I was at the kitchen table doing the thing I always do after a trip, which is putting every charge where it belongs. My wife walked past, looked at the screen, and asked why I was still working on the vacation.
As far as she was concerned, the vacation had been paid for in March.
That is not a small disagreement about bookkeeping. It is two different and completely coherent models of what a trip costs, and it took me longer than it should have to admit that hers is doing real work.
Her model: the expense was the transfer
For a year we had been moving $650 a month out of checking and into the high-yield savings account, into a bucket labeled Hawaii. Once that money left checking it was gone. Committed. Spoken for.
So when we were standing at a shave ice window on the North Shore, that was not spending in any meaningful sense. It was withdrawing from a fund that had already been paid for out of some earlier month’s income. Under her model the trip cost us $650 a month for twelve months and then cost nothing at all. The expensive part was the year of not spending. The week itself was free, because we had already done the hard part.
I want to be fair to this, because I think most people who are good with money run some version of it. It is the envelope method. You decide in advance what a thing is allowed to cost, you set the money aside, and then you stop thinking about it. The entire point is that the decision happens once, ahead of time, when you are calm and looking at a spreadsheet, rather than in a gift shop at the end of a long day.
My model: both things happened, on two different statements
Here is where the former accountant shows up.
I don’t think the transfer was the expense. I also don’t think the transfer was nothing. Both events are real, both get recorded, and the reason they neither cancel out nor double up is that they land on two different financial statements.
Every business keeps both. Households have exactly the same two, whether or not anyone ever writes them down.
The balance sheet is a snapshot. What you own minus what you owe, at one moment in time. It describes your position.
The income statement is a period. What came in minus what went out, over a month or a year. It describes your performance.
Moving $650 from checking into savings is a balance sheet event and only a balance sheet event. One asset goes down, another asset goes up by exactly the same amount, and your net worth at the end of that day is identical to what it was that morning. Nothing was consumed. Nothing left the household. You reorganized.
This is the part I keep coming back to. If moving money into savings were an expense, then saving would make you poorer, and every disciplined month would show up as a bad month. That cannot be right. It isn’t right because the income statement never sees the transfer at all.
The expense is the shave ice. The rental car, the hotel, the flights, and the sunscreen we forgot to pack and then bought at four times the mainland price. That is the moment the money actually left, and the month it left is the month it belongs to.
Why this isn’t a pedantic argument
I would happily let this go if picking the wrong model didn’t break anything. It breaks three things.
Count both, and you charge yourself for the trip twice. $7,800 into savings across the year, $7,412 spent in Hawaii, and your annual expense total now says the vacation cost $15,212. It didn’t. That number is fiction, and it is the single most common error I see in home budgets, because in a bank feed both legs look exactly like ordinary transactions. Nothing about the raw data tells you one of them was internal.
Count only the transfer, and August looks free. Next year you will sit down to plan another trip with no idea what a trip costs, because the only record of this one is twelve identical $650 rows labeled “savings” and a blank space where the vacation actually happened.
Count only the spending, and the arithmetic is right but you have thrown away the thing my wife cares about. August shows a $7,412 hole with no explanation attached to it. Nothing anywhere says that hole was funded on purpose, twelve months in advance. An income statement on its own cannot tell the difference between a vacation you saved for and a vacation you put on a credit card. Those are wildly different events in a household, and on a spending chart they are indistinguishable.
We were answering different questions
The argument dissolved once I stopped trying to win it.
She was never making a claim about the income statement. She was making a claim about the balance sheet, and her claim was true: by the time we got on the plane, the Hawaii money already existed, sitting in savings, and no part of that week was going to touch our regular cash flow.
Her question is “is it funded.” That is a level, a balance at a point in time. My question is “what did it cost.” That is an amount over a period. Neither one can be answered with the other. A savings balance cannot tell you whether $7,412 for a week is reasonable. A spending total cannot tell you whether you are on pace for next year.
Why the budget and the savings goals are separate pages
This disagreement is the specific reason those are two pages in Telemetry rather than one.
Merging them was tempting. They both involve money, they are both about the future, and one page is simpler than two. But they are different statements, and collapsing them into a single view forces exactly the double count above. So they stayed apart, and three things hold the line.
The savings account is marked as not budget-tracked. Money moving into or out of it never reaches a budget total, no matter how the transaction ends up categorized. That one flag is what makes the double count structurally impossible rather than something you have to remember every month.
A savings goal is a balance, not a spending category. Contributions raise it. When we pulled the money back out for the trip, the withdrawal lowered it. Over the year the Hawaii goal climbed from zero to its target, and over one week it went back to zero. That is the balance sheet story, and it is complete on its own without touching the budget.
The charges themselves categorize like any other spending, in the month they happened. Flights in March, because that is when we booked them. Everything else in August. When I look at August, the trip is right there in the total, because in August we did in fact spend that money.
Both statements end up true at the same time. Our net worth did not move on the days we saved. It moved on the days we spent. The goal shows a year of funding and a week of drawdown. The budget shows twelve ordinary months and one expensive August.
The last word went to her, sort of
I showed her the two views side by side. She looked at the goal, saw it back at zero, and said that was the only number she needed.
Then she looked at August, and said the number was higher than she thought it would be.
We were both right about that too. So we are still keeping our own books. She reads the balance sheet, I read the income statement, and the software’s job is to keep the two from arguing.
Get new posts by email
Occasional writing on net worth, the options wheel, and budgeting. No spam, unsubscribe anytime.